Follow the Coalition at COP31

Follow the Coalition at COP31
Read More

Coalition of Finance Minister events, reports, tools, and highlights 

The Coalition is dedicated to providing insightful news updates on global efforts and progress in country domestic climate action we support


The first Action Areas of the updated Flagship Guide are now open for consultation.

Coalition members and other interested stakeholders are invited to review the drafts and share their feedback, country experience, and implementation lessons to help make the final Guide as practical and useful as possible for Ministries of Finance. 

Contribute through the consultation form

Explore the consultation draft on the interactive website and share your feedback

Read the two-page summary for policymakers.

Consultation until 30 November 2026 


The Network for Greening the Financial System (NGFS) and the Coalition of Finance Ministers for Climate Action (CFMCA) have launched a new joint dialogue platform to deepen knowledge sharing between central banks and finance ministries on the macroeconomic dimensions of climate change and the transition to a low-carbon economy.

COP 31 Press Release

Check the previous and upcoming joint events here.


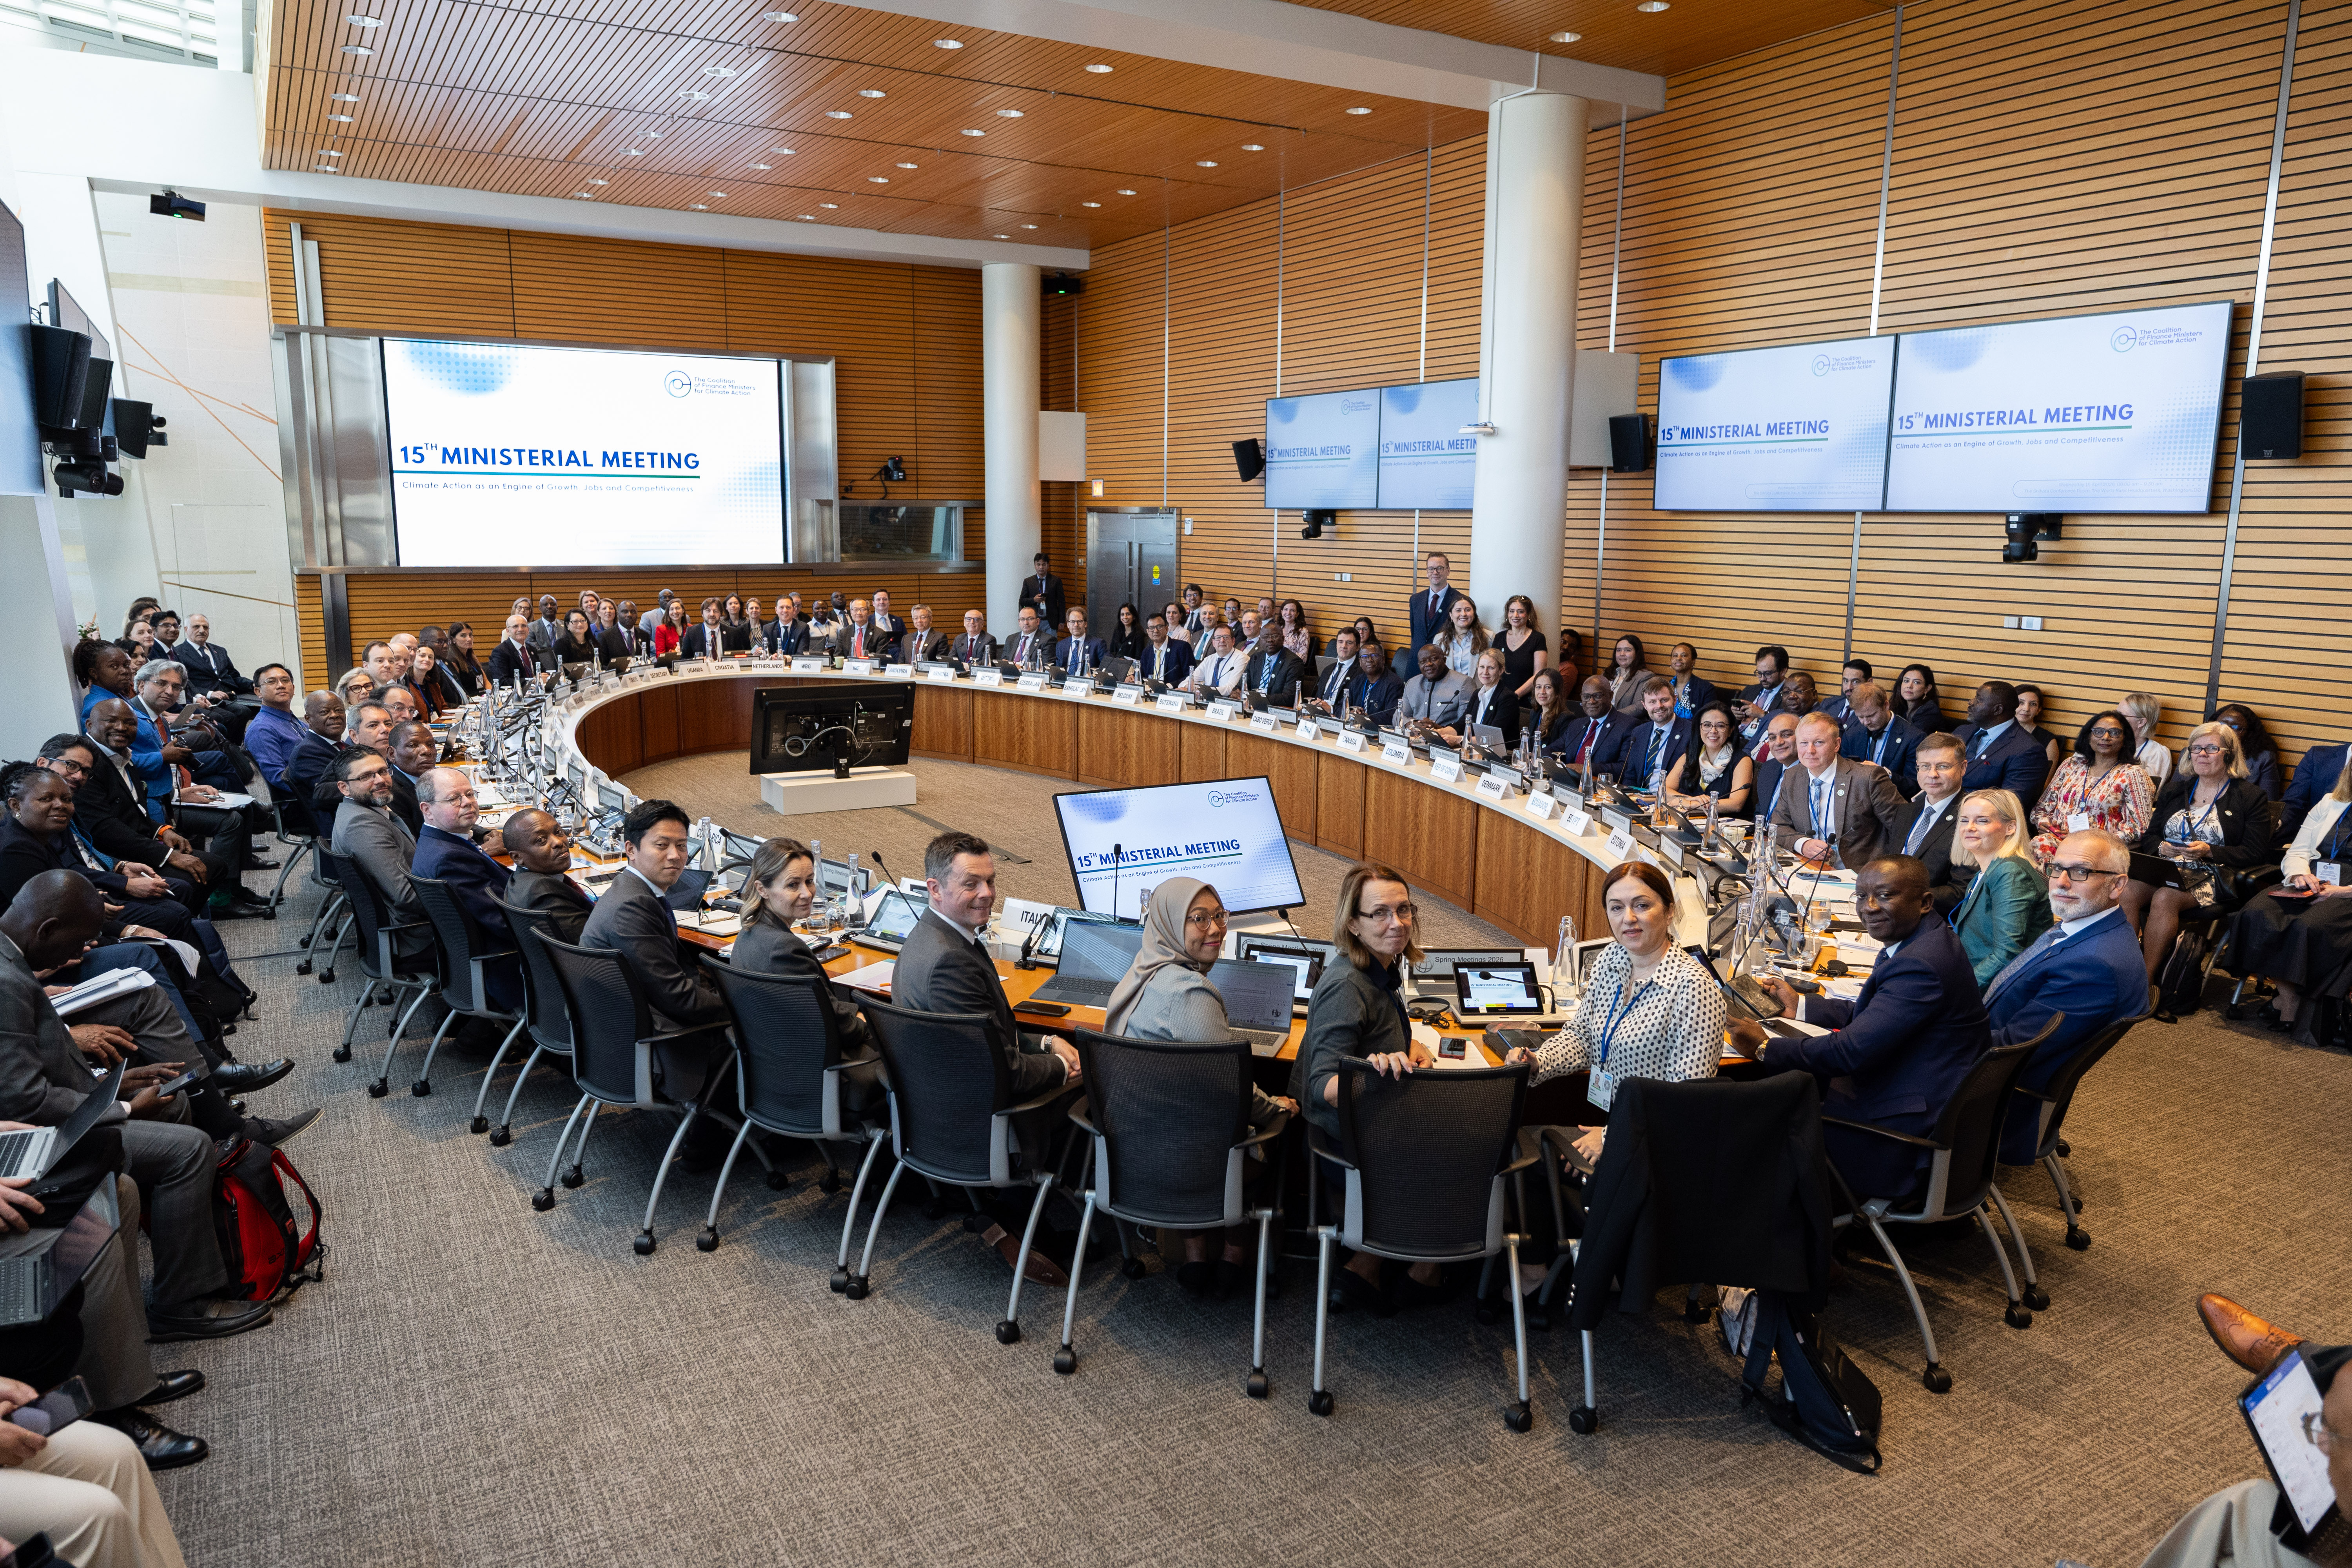
The Coalition’s program in Bangkok brings together ministerial leadership, regional and technical dialogue, and practical exchanges on climate and economic policy and reflects its growing focus on implementation, peer exchange and strengthening the role of Finance Ministries in climate action.
 
Read our main outcomes:
 

And follow us on LinkedIn for daily updates.


About the Coalition

Finance Ministers hold the keys to accelerating climate action. They are most clearly aware of the risks posed by climate change and recognize how taking action could unlock trillions in investments and create millions of jobs by 2030.

The Coalition of Finance Ministers for Climate Action brings together fiscal and economic policymakers from 100 countries to lead the global climate response and secure a just transition towards low-carbon, resilient development.

100+ Member Countries

Member Countries


From Vulnerability to Viability: The Cabo Verde Blueprint for Integrating Climate Action into Economic Policy

September 09, 2026

From Vulnerability to Viability: The Cabo Verde Blueprint for Integrating Climate Action into Economic Policy


By the Ministry of Finance of Cabo Verde

Cabo Verde's reform experience demonstrates how climate adaptation can be reframed from an environmental expenditure into a strategic investment in fiscal resilience, economic credibility, and long-term development. While important constraints remain, the country's approach offers practical lessons for integrating climate considerations into economic governance in vulnerable contexts.

When severe flooding forced Cabo Verde's government to redirect resources equivalent to 1.5 percent of its national budget toward emergency recovery, climate change ceased to be a distant environmental concern and became an immediate macroeconomic challenge. For a Small Island Developing State (SIDS) already exposed to external shocks, the episode revealed just how vulnerable public finances can be when climate risks are addressed only after disasters occur.

Article content
Main climate risks affecting Cabo Verde, Contribuição Nacionalmente Determinada 3.0, p.13

The experience became a turning point. Rather than viewing climate resilience as a sectoral issue led primarily by environmental institutions, policymakers recognized that climate risk directly affects fiscal stability, debt sustainability, investment decisions, and long-term growth prospects. In practice, this implied a stronger leadership role for the Ministry of Finance, acknowledging the direct implications of climate risks for fiscal and macroeconomic planning.

Cabo Verde's response reflects a broader shift taking place across many emerging and developing economies. As climate-related losses rise, adaptation is no longer being treated primarily as an environmental objective but as a form of economic risk management. From this perspective, resilience investments help reduce future fiscal liabilities, protect productive assets, and preserve fiscal space for development priorities.

Article content
Table from the Coalition's Deptuies Meeting presentation

The benefits of this approach extend beyond project selection. By integrating climate parameters into fiscal decision-making, Cabo Verde has strengthened coordination across government institutions and improved the alignment of sectoral strategies, such as energy, water, and infrastructure, with broader fiscal objectives. The reforms also send an important signal to development partners, investors, and credit rating agencies that climate risks are being managed systematically rather than reactively.

At the same time, integrating climate and fiscal policy is neither straightforward nor cost-free. Resilience investments typically require significant upfront expenditures, while many of their fiscal and economic benefits materialize only over the medium and long term. For governments operating within narrow fiscal constraints, allocating resources to adaptation can mean difficult trade-offs with other pressing development needs.

Recognizing these constraints, Cabo Verde has sought to use public finance strategically. Rather than relying exclusively on direct public spending, the government is increasingly positioning public resources to mobilize concessional resources while gradually creating conditions for greater participation of blended and private finance. The objective is not only to finance climate action but also to maximize the development impact of limited fiscal resources.

Another important outcome has been the strengthening of climate governance arrangements. This has enabled closer coordination among ministries, municipalities, development partners, and financial institutions, while supporting the mainstreaming of climate considerations across planning, budgeting, and investment decision-making processes. These institutional reforms have helped establish a more coherent framework for managing climate-related risks and opportunities across the economy.

Article content
Selection of Climate Action documents in Portal do Clima

Yet financing remains only one part of the challenge. Effective climate-informed policymaking depends on robust data, analytical tools, and technical expertise to assess how climate risks affect growth, public finances, debt sustainability, and investment outcomes. Like many climate-vulnerable countries, Cabo Verde continues to build these capabilities. Mobilizing private investment also remains challenging in small markets, where perceptions of risk can limit capital flows despite efforts to strengthen the enabling environment and deploy supportive public instruments.

To strengthen policy continuity and domestic ownership, the reform agenda is supported by a climate law and a dedicated climate and environmental fund. These institutional mechanisms help clarify responsibilities across government, create greater policy certainty, and support the mobilization of resources in line with national priorities. Their long-term effectiveness, however, will depend on sustained political commitment and consistent implementation across electoral cycles.

What makes Cabo Verde's experience particularly relevant is that it demonstrates a fundamental change in how climate action can be framed within economic policy. By treating resilience as an element of fiscal sustainability and economic credibility, climate policy becomes less about complying with external commitments and more about managing systemic economic risk.

For highly indebted and climate-vulnerable economies, climate action is becoming an increasingly important part of a broader strategy to strengthen economic credibility. In this context, resilience is not only about reducing vulnerability but also about enhancing economic competitiveness and fiscal sustainability.

Learn more: https://portaldoclima.gov.cv/entidade/acao-climatica-agora-pt/

Green Climate Fund for Cabo Verde: https://portaldoclima.gov.cv/en/2026/07/07/cabo-verde-steps-up-climate-action-with-support-from-the-green-climate-fund-gcf/
Latin America’s Regional Platform: A Blueprint for Climate‑Informed Fiscal Policy

July 23, 2026


blog

By the Colombian Ministry of Finance

Latin America’s regional platform for ministries of finance offers a practical model for integrating climate priorities into fiscal policy. By combining member-led governance, targeted capacity-building, and shared regional priorities, the platform shows how finance ministries can move from climate ambition to implementation, while strengthening access to finance, institutional readiness, and regional cooperation.

At a time when ministries of finance are increasingly expected to act as fiscal stewards and climate strategists, Latin America has been building one of the most structured regional responses to this dual mandate. Launched in 2022 under the mandate of the Inter‑American Development Bank (IDB), the Climate Change Platform for Ministries of Finance and Economy has evolved into a practical laboratory for fiscal innovation, multilateral cooperation, and institutional learning.

Article content
Photo from IDB MEF website

From the start, the platform was designed as a structured regional mechanism. It operates through binding annual work plans, ministerially endorsed priorities, and thematic working groups designed to reflect the core fiscal dimensions of climate action. In just three years, it has trained more than 185 officials, generated a shared technical language on green finance, and helped align climate finance strategies with domestic macro‑fiscal objectives across the region.

At its core, the platform pursues three closely linked objectives: integrating climate considerations into fiscal and macroeconomic policy; supporting the development of nationally aligned climate strategies; and shaping a coherent regional voice in international economic and climate negotiations. These priorities reflect a deliberate shift away from treating climate policy as an environmental issue, and toward integrating it firmly within ministries’ central economic and budgetary functions.

This orientation is reinforced through four thematic working groups: Debt and Green Financing, Revenue and Tax Incentives, Public Climate Expenditures, and Biodiversity and Natural Capital, which place finance ministries at the center of managing transition costs, mobilizing concessional resources, and integrating natural capital into fiscal frameworks. Importantly, countries co‑lead these groups, and this design promotes ownership and accountability, ensuring that regional cooperation delivers outcomes that are useful and relevant for individual countries.


Article content
Numbers from IDB website

The platform’s governance model is one of its defining strengths. It is explicitly member‑led and member‑owned, with ministries collectively defining priorities, co‑chairing working groups, and endorsing deliverables. As a result, the platform has remained credible and stable over time, while still being able to respond to changing fiscal and political context. The model is further strengthened by pooling resources, bringing together IDB support and funding from key partners such as the German government through the IKI Fund.

In practice, this applies the Coalition’s approach at the global level, where effective climate‑fiscal action depends on aligning technical assistance, concessional finance, and domestic institutional capacity.

Challenges of Scale and Sustainability

Access to international climate finance has emerged as one of the most pressing challenges identified by member states. Despite the proliferation of concessional windows, blended finance facilities, and innovative instruments, many Latin American countries continue to struggle when converting these opportunities into effective financing. Weak project preparation capacity, fragmented institutional arrangements, and limited experience with increasingly complex financial instruments have slowed the development of projects ready for financing.

The platform operates with a small team at its core, relying on continued ministerial engagement and IDB support. Long‑term financing continues to depend on external partners, underscoring the importance of diversified resource mobilization. Rather than relying on firm budget guarantees, its strength has come from its members' commitment and shared ownership, enabling it to deliver real policy results even with limited resources.

Additionally, the platform has adopted a targeted, pragmatic approach rather than responding with generic best‑practice exchanges. Discussions are structured around diagnosing the specific constraints faced by finance ministries, grounded in systematic needs assessments. This has sharpened the platform’s focus on institutional readiness, pipeline development, and the strategic use of innovative instruments, while supporting a coordinated regional effort to expand access to concessional finance and ensure that such resources can be effectively deployed within national fiscal frameworks.

Knowledge generation and capacity‑building are tools for implementation. The platform supports peer‑to‑peer exchange through a dedicated internal digital space that hosts policy documents, workshop outputs, and monitoring data. This infrastructure is complemented by a follow‑up mechanism designed by the ministries themselves, linking work plans to concrete deliverables and tracking how knowledge‑sharing translates into policy action. In its first iteration, covering 13 countries, 85 percent of respondents reported that platform outputs were useful in advancing national policy implementation, an outcome‑oriented metric that remains uncommon in multilateral initiatives.

A major milestone was reached in 2023, when ministers adopted a shared regional vision on green finance at their meeting in Belize. The vision provides a common reference point for taxonomies, debt management tools, and budgetary alignment with climate objectives, while strengthening the region’s collective voice in international forums. For other regions considering similar approaches, it provides a clear reference point for embedding climate considerations into fiscal policy.

In a global climate finance landscape often criticized for its complexity and fragmentation, Latin America’s experience demonstrates the value of well‑designed regional platforms. By embedding climate considerations into fiscal policy, pooling resources, and measuring success through implementation rather than outputs alone, ministries of finance can position themselves as central actors in delivering economic stability and climate resilience.

More information: https://www.iadb.org/en/who-we-are/topics/climate-change/climate-change-finance/lac-regional-climate-change-platform

Read our blog on Finance Ministries and Country Platforms: https://www.linkedin.com/pulse/finance-ministries-country-platforms-strategic-yahkf/?trackingId=tNDv27m5Q%2Fe1ijYokpLpBA%3D%3D

Securing the Future: How Italy Is Tackling the Insurance Protection Gap

August 10, 2026


By the Italian Ministry of Finance

Italy has introduced a pioneering public–private insurance scheme mandating business coverage for natural catastrophes, aiming to close its 78% protection gap and set a model for international disaster risk finance.

Italy is one of Europe's most hazard-exposed countries, where earthquakes, floods, and landslides pose persistent risks and where the economy relies heavily on small and medium-sized enterprises (SMEs), many of which lack adequate insurance protection. For example, when devastating floods struck Emilia Romagna in 2023, the damage bill reached billions of euros, much of it uninsured. The disaster underscored a growing challenge for Italy and many countries worldwide: natural catastrophes are becoming more frequent and costly, while insurance coverage remains insufficient.

Today, an estimated 78% of potential losses from natural disasters in Italy are uninsured, leaving businesses vulnerable, slowing recovery, and increasing pressure on public finances.

Recognizing the economic and fiscal costs of this protection gap, Italy has introduced an ambitious reform to promote risk prevention and management, reduce fiscal exposure, and encourage public-private cooperation, while improving long-term budget sustainability.

A Landmark Reform

In late 2023, Italy introduced a groundbreaking measure through its 2024 Budget Law. The legislation requires all registered companies operating in Italy, except for agricultural businesses, as well as foreign ones with a permanent establishment in Italy, to insure land, building, plants, machinery, and industrial and commercial equipment for the reconstruction value, and the restoration and replacement costs, against three major natural hazards: earthquakes, floods, and landslides. At the same time, insurers must offer this coverage with risk-based premiums that reflect location, vulnerability, and the prevention measures adopted, to incentivize firms to invest in adaptation and resilience while ensuring that coverage is available across the market. Insurance premiums are updated periodically to reflect the economic conditions and the specific risk of the companies.

Implementation has been phased in gradually. Large companies were the first asked to comply by March 31, 2025, while small and micro enterprises are joining the scheme by December 31, 2025. The gradual rollout reflects the government's objective of expanding protection while allowing businesses and insurers time to adapt.

Although residential property and infrastructure are not yet included, the reform marks a major shift in how disaster risk is shared and managed across the economy.

Sharing Risk Through Public–Private Partnership

At the heart of the initiative is an innovative public–private partnership designed to make catastrophe insurance both viable and sustainable.

SACE, Italy's state-owned export credit agency, plays a central role as a reinsurer of last resort. SACE can cover up to 50% of insurers’ liabilities through a proportional reinsurance model, providing confidence that even large-scale events can be covered without destabilizing the market.

Article content
The public guarantee scheme

This mechanism allows private insurers to underwrite risks that might otherwise be difficult or too costly to absorb. Premiums collected from policyholders finance the scheme in the first instance, while the state provides an additional safeguard in the event of extreme systemic losses, with support of up to €5 billion annually in 2025 and 2026.

The long-term objective is clear: build a mature and resilient insurance market in which private actors progressively assume a greater share of risk, while public support remains available for truly exceptional events.

To balance affordability with market discipline, the legislation also establishes differentiated rules on deductibles, coverage limits, and premium structures, reflecting the diverse circumstances of micro-enterprises, SMEs, and larger firms.

Building Policy on Evidence

The reform is the result of extensive analytical work and collaboration across sectors. The Ministry of Economy and Finance partnered with civil protection authorities, insurers, and industry associations to develop detailed risk assessments, historical loss databases, and forward-looking catastrophe models.

This evidence-based approach helped ensure that the scheme reflects Italy's territorial realities while supporting sound, sustainable pricing.

During its 2024 G7 Presidency, Italy developed a High-Level Framework for Public–Private Insurance Programs Against Natural Hazards. The framework provides practical step-by-step guidance for governments seeking to reduce protection gaps through structured partnerships, involving, in particular, policy makers, insurance regulators, and supervisors - rather than relying exclusively on post-disaster public compensation.

Italy has also advanced this agenda within the G20 Sustainable Finance Working Group, which it co-chaired in 2025 under South Africa's Presidency. Discussions focus on how insurance solutions can strengthen resilience not only in advanced economies but also in emerging and developing countries, where exposure to climate-related risks is rising while fiscal resources remain constrained. This work culminated in the development of a set of recommendations to scale up adaptation investment and reduce insurance protection gaps, framing insurance protection as part of broader, multi-layered disaster risk finance strategies, in which different tools address different layers of risk depending on their frequency and severity.

At the European level, Italy is contributing to a new dialogue on disaster risk financing and insurance innovation, helping shape approaches that combine resilience, affordability, and fiscal sustainability.

A Blueprint for the Future?

Italy's experience highlights a fundamental question facing policymakers worldwide: how can governments mobilize private capital to strengthen resilience while ensuring that essential protection remains affordable?

The answer increasingly lies in multi-stakeholder partnerships. Mandatory coverage expands participation and creates more predictable recovery mechanisms, while public support helps absorb catastrophic tail risks that markets alone may struggle to manage.

Challenges remain. Some observers argue that households should eventually be included, while others point to emerging climate threats such as droughts, heatwaves, and severe storms that fall outside the current scope.

As climate and disaster risks continue to escalate, countries around the world will need innovative ways to protect citizens, businesses, and public finances. Italy's model, combining mandatory coverage, public reinsurance, and a phased implementation strategy, offers one possible path forward.

In taking decisive action to close its protection gap, Italy has done more than strengthen its own resilience. It has demonstrated how insurance can become a powerful tool for climate adaptation, fiscal stability, and long-term economic security.